Home Loan Philippines: Requirements, Process, and Costs
Key Takeaway
- A home loan and a housing loan generally refer to financing used to purchase a residential property.
- Home loan eligibility and financing options depend on the lender’s requirements, your financial assessment, supporting documents, and property eligibility or appraisal, where applicable.
- Before applying, compare repayment costs, fees, loan conditions, and available financing options.
Buying a home is a major financial commitment, and choosing the right property is only part of the process. Before applying for a home loan, it helps to understand eligibility requirements, necessary documents, property appraisal, and repayment responsibilities. These factors can affect your financing options and long-term budget.
Learn how home loans work in the Philippines, including requirements, property appraisal, repayment costs, and financing options. This guide walks you through what to expect, what costs to consider, and how to compare available options, helping you make informed decisions before taking the next step toward homeownership.
What Is a Home Loan and How Does It Work?
A home loan is a type of financing commonly used to purchase residential property, such as a house, townhouse, or condominium. Instead of paying the full property price upfront, you borrow money from a lender and repay it over an agreed period, including applicable interest and fees.
The property typically serves as collateral, giving the lender security for the loan. You’ll make regular payments based on your loan agreement, so it’s important to understand the total borrowing costs, repayment schedule, and loan conditions before committing.
Home Loan vs Housing Loan: Is There a Difference?
In the Philippines, “home loan” and “housing loan” are often used interchangeably. Both generally refer to financing for residential property.
However, loan purposes, eligibility requirements, repayment terms, and fees may vary by lender. Always review the specific product details to understand what’s covered before applying.
What Can a Home Loan Be Used For?
Depending on the lender and financing product, a home loan may support different housing-related needs, including:
- Buying a home: Purchasing a house, townhouse, condominium, or other eligible residential property.
- Building a house: Financing the construction of a residential property.
- Home renovation: Covering eligible repairs or improvements to an existing home.
- Refinancing: Replacing an existing housing loan with a new loan under different terms.
Not every lender offers financing for all these purposes. Check the available loan options, property eligibility, and requirements to find financing that matches your plans and repayment capacity.
Types of Home Financing in the Philippines
There are several ways to finance a home in the Philippines, including bank housing loans, government-backed housing programs such as Pag-IBIG Fund, and financing company options. Each comes with different eligibility requirements, property conditions, costs, and repayment terms.
The right option depends on your financial situation and purpose. Financing a new property purchase is different from borrowing against a property you already own, so understanding these options can help you decide where to start.
Housing Loans for Property Purchases
Housing loans for property purchases help you buy a residential property without paying the full price upfront. You repay the borrowed amount according to the agreed terms, including applicable interest and fees.
Before applying, check which property types are eligible, whether the property meets the lender’s requirements, and how much you may need to cover upfront.
Loans Secured by Existing Property
If you already own a property, you may be able to use the property as collateral to secure financing for eligible personal or business needs, subject to ownership verification, property appraisal, and the lender’s requirements.
Unlike a housing loan used to purchase a new home, this option allows you to borrow against property you already own, subject to the lender’s assessment and property appraisal.
Keep in mind that your property may be at risk if you fail to meet your repayment obligations. Review the loan terms, total costs, and repayment responsibilities before applying.
Home Loan Requirements and Eligibility
Before applying for a home loan in the Philippines, it’s helpful to know what lenders look for and which documents you may need. Lenders generally review your financial situation, repayment capacity, and property details to assess your application.
Home loan requirements and eligibility criteria vary by lender and financing product, so checking them early can help you prepare and avoid missing important documents.
Who May Qualify for a Home Loan?
Home loan eligibility typically depends on several factors, including:
- Age and Legal Capacity: You must meet the lender’s age requirements and be legally able to enter into a loan agreement.
- Identity Verification: You need valid identification to confirm your identity and personal details.
- Income and Employment: Lenders may review your income sources, employment status, or business earnings.
- Repayment Capacity: Your income, existing debts, and monthly expenses help lenders assess whether you can manage loan payments.
- Credit Assessment: Your credit history and existing financial obligations may affect the lender’s decision.
- Property Eligibility: The property must meet the lender’s requirements and may undergo an appraisal.
Meeting the basic requirements does not guarantee loan approval. Each application is subject to the lender’s assessment and applicable conditions.
Common Documents You May Need
Preparing your documents in advance can make the application process easier to manage. While requirements vary, lenders commonly request the following:
1. Personal Identification Documents
- Valid government-issued ID
- Completed loan application form
- Civil status documents, if applicable
2. Proof of Income and Financial Records
- Recent payslips or Certificate of Employment for employed applicants
- Income Tax Return (ITR), when required
- Bank statements or other financial records
- Business registration and income documents for self-employed applicants, if applicable
3. Property and Ownership Documents
- Transfer Certificate of Title (TCT) or Condominium Certificate of Title (CCT), as applicable
- Tax declaration and relevant property tax records
- Contract to Sell or other purchase documents, if applicable
- Additional property documents required for appraisal and verification
Your lender may request additional documents depending on your employment, financing purpose, and property type. Confirm the complete checklist before submitting your application.
How Does Property Appraisal Work for a Home Loan?
A property appraisal is the process of estimating a property’s market value based on its location, condition, features, and other relevant factors.
Before making a home loan decision, lenders use an appraisal to understand how much the property may be worth and whether it meets their financing requirements. This helps them assess the property offered as collateral and the risks involved in the loan.
What Does a Property Appraiser Check?
During a property appraisal, an appraiser typically reviews several factors, including:
- Location: The property’s neighborhood, accessibility, and nearby facilities.
- Physical Condition: The property’s age, maintenance, structural condition, and visible damage.
- Property Features: Lot size, floor area, layout, and type of residential property.
- Property Documents: Land titles, tax declarations, and other records needed to verify property details.
- Market Comparisons: Recent selling prices or available market data for similar properties in the area.
These factors help the appraiser estimate the property’s value, which may differ from its selling price or the owner’s expected value.
How Can Appraisal Affect Your Loan Application?
The appraised property value is one of the factors a lender may consider when assessing your application and determining the financing amount it may offer, alongside your financial profile and repayment capacity.
For example, if a property’s appraised value is lower than its selling price, you may need to prepare additional funds to cover the difference, depending on the lender’s financing terms.
However, a higher appraisal does not guarantee a larger loan or approval. Lenders also assess your income, repayment capacity, credit history, property documents, and other eligibility requirements before making a financing decision.
How to Apply for a Home Loan in the Philippines
Applying for a home loan involves more than filling out a form. You’ll need to check your budget, prepare documents, and understand the financing terms before making a commitment.
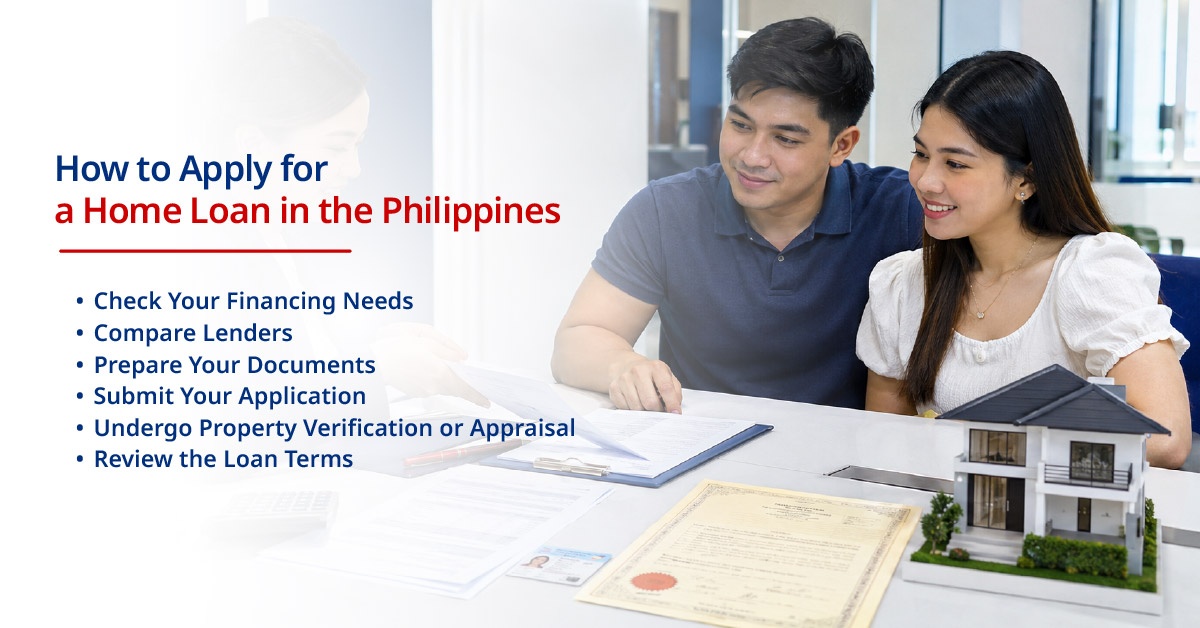
Here’s a simple step-by-step guide to help you get started:
- Check Your Financing Needs: Determine how much financing you need and whether your budget can handle regular repayments.
- Compare Lenders: Explore financing options and review their eligibility requirements, costs, and repayment terms.
- Prepare Your Documents: Gather the required identification, income records, and property documents.
- Submit Your Application: Complete the lender’s application form and provide the necessary information for assessment.
- Undergo Property Verification or Appraisal: If required, the lender will arrange property checks or an appraisal as part of the application assessment.
- Review the Loan Terms: Before accepting an offer, check the interest, fees, repayment schedule, and other obligations.
The application process may vary depending on the lender and financing product, so confirm the specific steps before applying.
What Happens After You Submit Your Application?
Once you’ve submitted your application, the lender generally reviews your documents, financial background, credit history, and repayment capacity. Property checks or an appraisal may also be required.
The lender will then assess your eligibility and decide whether to offer financing. Approval and loan terms depend on the assessment results, and additional documents may be requested during the process.
How to Apply for Asialink’s Real Estate Loan or Real Estate Financing
Asialink Finance offers two real estate options: Real Estate Financing for eligible ready-for-occupancy (RFO) property purchases and Real Estate Loan for borrowing against an existing property title.
You can start your inquiry or application through the following channels:
- Apply Online: Complete the Asialink Application Form or visit Asialink Onboarding.
- Visit a Branch: Speak with Asialink staff about financing options and document requirements.
- Contact the Online Sales Marketing Group: Email [email protected] or call 0917 851 6353 / 0917 808 9215.
The application generally involves submitting your form, preparing the required documents, and completing verification and assessment.
Because Real Estate Loan and Real Estate Financing have different requirements, it’s best to contact an Asialink representative to confirm which option fits your needs before applying.
Understanding Home Loan Interest Rates, Fees, and Repayments
Before taking out a home loan, it’s important to understand how much borrowing may cost beyond your monthly payments. Interest rates, repayment terms, and additional fees can all affect your overall expenses.
Knowing what to look for can help you compare financing options, plan your budget, and avoid unexpected costs.
What Affects Home Loan Interest Rates?
Home loan interest rates can vary depending on the lender and your financing arrangement. Common factors include:
- Lender and Loan Type: Different lenders and financing products may have different interest rate structures.
- Repayment Term: The length of your loan can affect the interest you pay over time.
- Financial Assessment: Your income, credit history, and repayment capacity may influence the terms offered.
- Market Conditions: Changes in the economy and lending market may affect interest rates.
Always confirm whether the interest rate is fixed or variable and how it may change during your repayment period.
How to Use a Home Loan Calculator
A home loan calculator can help you estimate potential monthly payments before applying. Most calculators ask for:
- Loan Amount: The amount you plan to borrow.
- Interest Rate: The rate used to estimate borrowing costs.
- Repayment Term: The period over which you expect to repay the loan.
The calculator uses these details to estimate your monthly payments. However, the results are for planning purposes only and do not represent an approved loan amount or a binding financing offer. Actual costs depend on the lender’s assessment and final terms.
Other Costs to Consider
Beyond interest, home financing may involve additional fees and charges, depending on the lender and property.
Depending on the financing product and agreement, additional costs may include property appraisal fees, documentation charges, insurance premiums, registration fees, or late-payment penalties. Confirm which charges apply before accepting any financing offer.
Not all fees apply to every loan. Ask your lender which charges are included, when they are payable, and whether any are deducted from the financing proceeds.
Understanding the Total Cost of Borrowing
Your monthly payment doesn’t tell the whole story. To understand the total cost of a home loan, consider the interest payable over the loan term, applicable fees, and other required expenses.
You may also come across the Effective Interest Rate (EIR), which helps you understand the annualized cost of borrowing by accounting for the timing of repayments and applicable financing charges under the relevant calculation rules.
Before accepting a financing offer, review the loan disclosure documents and repayment schedule. Confirm which fees apply to your arrangement, how much you are expected to repay, and what happens if you miss a payment.
Understanding these details can help you choose financing that fits your budget and long-term responsibilities.
Bank vs Financing Company: Which Should You Consider?
When looking for a home loan in the Philippines, you may consider banks or financing companies. Both can offer property-related financing, but their products, requirements, and assessment processes may differ.
The right choice depends on your financing needs, financial situation, and repayment capacity. Rather than focusing only on the lender type, compare what each provider offers and the responsibilities that come with borrowing.
Differences in Products, Requirements, and Assessment
Banks and financing companies may differ in how they structure and evaluate home financing applications.
- Financing Products: Banks commonly offer housing loans for property purchases, while financing companies may offer property purchase financing or loans secured by existing property.
- Eligibility Requirements: Each lender sets its own income, credit, and documentation requirements.
- Application Assessment: Lenders may review your financial background, existing debts, repayment capacity, and credit history.
- Collateral Policies: Property eligibility, appraisal methods, and security requirements can vary by provider.
Neither option automatically guarantees approval or better loan terms. Each application is evaluated according to the lender’s policies.
What Should You Compare Before Choosing a Lender?
Before applying, compare these important factors to see which financing option suits your needs.
| Factor | Banks | Financing Companies |
|---|---|---|
| Loan Products | May offer housing loans for eligible property purchases and other housing purposes | May offer property purchase financing or loans backed by existing property |
| Requirements | Depend on the bank and loan product | Depend on the company and financing product |
| Credit Assessment | May assess income, credit history, existing obligations, and repayment capacity. | May assess income, credit history, existing obligations, and repayment capacity based on their lending policies. |
| Collateral | Property security and appraisal may be required | Collateral and appraisal requirements depend on the product |
| Interest and Fees | Based on the bank’s specific loan terms | Based on the financing company’s specific terms |
| Repayment Terms | Vary by product and agreement | Vary by product and agreement |
Look beyond the interest rate when comparing lenders. Review the total cost of borrowing, monthly payment schedule, applicable fees, repayment risks, and loan disclosure documents.
Most importantly, choose a financing product that matches your purpose and fits your repayment budget, whether it comes from a bank or a financing company.
Risks and Responsibilities Before Taking a Home Loan
A home loan is a long-term financial commitment, so it’s important to understand your repayment responsibilities and the risks involved before signing an agreement.
Missing payments may lead to additional charges and could put your property at risk if it’s used as collateral. Before borrowing, make sure the repayment terms fit your budget and that you understand what happens if you cannot meet your obligations.
What Happens If You Miss a Payment?
If you miss a home loan payment, the consequences depend on your loan agreement and the lender’s policies. These may include:
- Late-Payment Charges: Additional fees or penalties may apply to overdue payments.
- Collection Procedures: The lender may contact you about unpaid amounts and take steps to collect the outstanding balance.
- Credit History Impact: Missed payments may affect your credit record and future borrowing opportunities.
- Risk to Your Property: Continued nonpayment may lead to foreclosure or other legal action involving the collateral, subject to the loan agreement and applicable law.
Missing a payment does not automatically mean your property will be foreclosed. However, continued default may lead to legal action or enforcement of the collateral, depending on your loan agreement and applicable law. Contact your lender early if you expect difficulty making payments.
How to Assess Your Repayment Capacity
Before applying, take a closer look at your finances to see whether you can manage regular loan payments.
- Review Your Income: Consider how much you regularly earn and whether your income is stable.
- List Essential Expenses: Account for food, utilities, transportation, housing, and other daily needs.
- Check Existing Debts: Include credit card payments, personal loans, and other financial obligations.
- Set Aside Emergency Savings: Keep funds available for unexpected expenses or temporary income changes.
- Plan for Long-Term Costs: Consider how future expenses or changes in income could affect your ability to repay.
A loan should fit your financial situation, not stretch your budget beyond what you can manage. Review the repayment schedule, total borrowing costs, and contract conditions before making your decision.
Conclusion
Choosing a home loan in the Philippines starts with understanding your financing needs, eligibility, and repayment capacity. From preparing documents and reviewing property appraisals to comparing lenders, every step matters. Look beyond monthly payments and consider total borrowing costs, applicable fees, and potential risks. Whether you’re buying a home or borrowing against an existing property, choose financing that matches your goals, budget, and long-term financial responsibilities.
Asialink Finance Corporation is an SEC-regulated Philippine financing company offering property-related financing options. Its Real Estate Loan provides financing secured by eligible existing real estate, while Real Estate Financing supports the purchase of eligible ready-for-occupancy (RFO) properties. Both products are subject to their respective eligibility requirements and assessment processes.
Explore Asialink’s official products, check requirements, and compare options before applying.
FAQs
Can I apply for a home loan online?
Yes, many lenders in the Philippines accept online home loan applications. You can apply for eligible property financing products through Asialink Finance’s online application form. Check the specific requirements and prepare your documents before submitting your application for assessment.
How can I estimate monthly home loan payments?
You can use a home loan calculator by entering your estimated loan amount, interest rate, and repayment term. The calculator provides an estimated monthly payment, but actual costs may differ depending on the lender’s fees, assessment, and final financing terms.
Can I use my property title as collateral?
Yes, some lenders offer loans secured by property you already own. You may need to provide the property title and other ownership documents for verification and appraisal.
Asialink Finance’s Real Estate Loan is one option to explore. Eligibility depends on property ownership, appraisal, document verification, repayment capacity, and the lender’s assessment. Approval is not guaranteed.
How long does the home loan application process take?
Home loan processing times vary depending on the lender, document completeness, financial assessment, and property appraisal requirements. Additional verification may also be necessary. Ask your chosen lender about the application process and possible next steps before submitting your documents.
What is ready-for-occupancy property financing?
Ready-for-occupancy (RFO) property financing helps eligible buyers finance the purchase of completed residential properties that are ready for occupancy, subject to the lender’s property eligibility requirements and assessment.
Asialink Finance offers Real Estate Financing for eligible RFO purchases, subject to property assessment, borrower eligibility, documentation requirements, and applicable financing terms.