What Is a Mortgage and How Does a Mortgage Loan Work?
Key Takeaway
- A mortgage is a legal arrangement that uses real property as collateral to secure a debt, while the borrower remains responsible for repaying the loan.
- A real estate mortgage generally involves immovable property, such as land or a house, while a chattel mortgage involves movable assets, such as vehicles.
- During a mortgage loan, the borrower generally retains ownership of the property, but it remains subject to the mortgage. The lender may also keep original title documents under the financing agreement.
- Mortgage Redemption Insurance (MRI) may help settle an outstanding mortgage obligation if the insured borrower dies, subject to the insurance policy’s coverage, exclusions, and conditions.
Understanding what a mortgage is can help you make informed decisions before using property as collateral for financing. A mortgage connects a debt to an asset, such as land or a house, and creates responsibilities that continue until the secured obligation is satisfied.
Before applying for a mortgage loan in the Philippines, it is important to understand how collateral works, what happens to your property title, and what could happen if you cannot meet your repayment obligations.
This guide explains these concepts, including the difference between real estate and chattel mortgages, the purpose of mortgage insurance, and the details you should check before signing a financing agreement.
What Is a Mortgage?
A mortgage is a legal arrangement in which property serves as collateral for a debt or financial obligation. It gives the lender a security interest in the property while the borrower remains responsible for repayment.
Under Article 2124 of the Philippine Civil Code, immovable property and certain real rights over immovable property may be the object of a mortgage.
The arrangement generally involves three important principles:
- Property as collateral: An eligible property secures the borrower’s financial obligation.
- Repayment responsibility: The borrower must make payments according to the agreed financing terms.
- Legal consequences: Failure to fulfill the obligation may allow the lender to enforce its rights over the collateral, subject to the agreement and applicable law.
A mortgage does not automatically transfer ownership of the property to the lender. However, if the borrower fails to fulfill the secured obligation, the lender may pursue foreclosure or other enforcement remedies permitted under the agreement and applicable laws.
How Does a Mortgage Work?
A mortgage involves four key elements: the borrower, the lender, the property, and the secured debt. Each plays a specific role in the financing arrangement.
The process generally follows these steps:
- Financing application: The borrower applies for a mortgage loan and provides information about their finances and proposed collateral.
- Property evaluation: The lender reviews the property’s ownership documents, condition, location, and appraised value.
- Mortgage documentation: If the application is approved, the parties execute the required financing and mortgage documents.
- Loan repayment: The borrower makes payments according to the agreed schedule, including applicable interest and fees.
- Mortgage release: Once the secured obligation has been fully satisfied, the lender processes the appropriate release documents and related requirements.
For example, a property owner may apply for financing to support business operations and offer an eligible property as collateral. The lender evaluates both the property and the borrower’s capacity to repay.
Approval depends on the overall assessment, not simply on property ownership or value.
Documentation, registration, repayment arrangements, and release procedures may differ depending on the lender, financing product, and transaction.
What Property Can Be Used as Collateral?
Real property may be considered as collateral when it meets the applicable legal and lender requirements.
Common examples include:
- Land: A parcel of land with appropriate ownership documentation.
- House and lot: Residential property consisting of land and a house.
- Condominium: A qualifying condominium unit supported by the necessary ownership documents.
- Other eligible real estate: Certain properties that meet the financing provider’s requirements.
Lenders usually consider legal ownership, property condition, market value, location, and existing restrictions before determining eligibility.
Not every property qualifies for every financing product. A property with unresolved ownership issues or existing legal claims, debts, or restrictions may require further review.
Movable assets, such as vehicles, generally fall under a different category of secured financing, including chattel mortgages or other personal-property security arrangements.
What Is the Difference Between a Mortgage and a Chattel Mortgage?
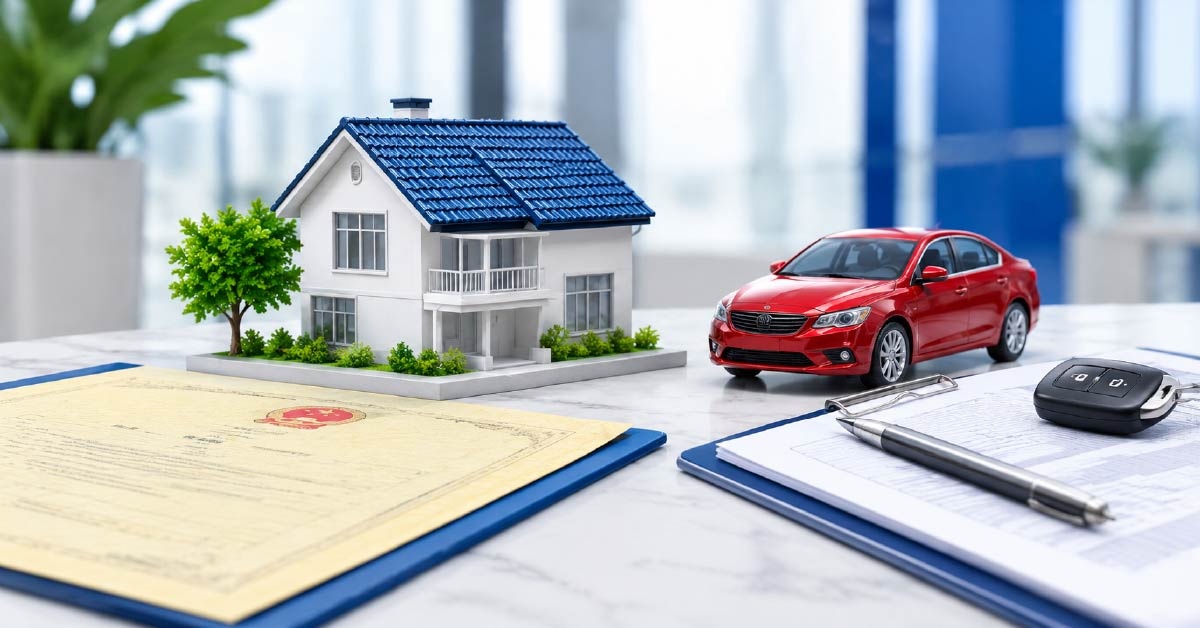
The main difference between a mortgage and a chattel mortgage is the type of property used as security.
A real estate mortgage generally involves immovable property, while a chattel mortgage involves movable or personal property. Both arrangements secure an obligation, but their documentation and applicable legal requirements differ.
Mortgage for Real Property
A real estate mortgage uses eligible immovable property as collateral.
Examples include:
- Residential or commercial land
- House-and-lot properties
- Condominium units
- Other qualifying real estate
The property remains subject to the mortgage while the secured obligation is outstanding.
Under the Philippine Civil Code, a mortgage is connected to a principal obligation and must satisfy applicable ownership, authorization, and legal requirements.
The lender may also require property inspection, valuation, title verification, and supporting financial documents.
Whether a particular property qualifies depends on its legal status, ownership records, and the financing provider’s product guidelines.
Chattel Mortgage for Movable Property
A chattel mortgage generally uses movable or personal property as security for an obligation.
A common example is a motor vehicle.
For instance, a borrower may use an eligible vehicle to secure financing. The financing agreement identifies the asset and establishes the lender’s security rights.
The borrower remains responsible for making the required payments.
In the Philippines, Republic Act No. 11057, or the Personal Property Security Act, also provides a legal framework for security interests in personal property. The applicable documentation and registration procedures depend on the transaction and relevant legal requirements.
A chattel mortgage should not be confused with a real estate mortgage, even though both involve collateral-backed financing.
Mortgage vs Chattel Mortgage: Key Differences
The following table summarizes the basic differences.
| Topic | Mortgage | Chattel Mortgage |
|---|---|---|
| Typical collateral | Immovable or real property | Movable or personal property |
| Examples | Land, house and lot, qualifying condominium | Vehicle or other eligible movable asset |
| Purpose | Secure a debt or financial obligation | Secure a debt or financial obligation |
| Documentation | Real estate mortgage and related security documents | Chattel mortgage and applicable security documents |
| Ownership | Borrower generally retains ownership, subject to the mortgage | Borrower generally retains ownership, subject to the security arrangement |
| Legal requirements | Real property and land registration requirements | Applicable personal-property security and registration requirements |
Both arrangements involve repayment obligations and potential consequences if the borrower defaults.
The appropriate structure depends on the collateral, financing purpose, agreement, and applicable laws.
What Happens to the Property Title During a Mortgage Loan?
One common concern when applying for a mortgage loan is whether the lender takes ownership of the property or keeps its title.
It is important to distinguish between property ownership, the mortgage recorded against the property, and physical custody of the title document.
Does the Borrower Still Own the Property?
Generally, the borrower continues to own the property while it is mortgaged.
A mortgage creates a security interest connected to the debt. It does not automatically transfer ownership to the lender.
However, the property remains subject to the mortgage until the secured obligation is satisfied and the appropriate release procedures are completed.
This means:
- The registered owner generally retains ownership.
- The property serves as security for the outstanding obligation.
- The mortgage may affect transactions involving the property.
- Failure to fulfill the financing agreement may lead to enforcement proceedings permitted by law.
A missed payment does not automatically make the lender the property owner.
The lender must follow the applicable agreement and legal procedures when enforcing its rights.
What Happens to the Original Title?
A property’s registered ownership and the physical location of its title document are different matters.
Three concepts are important:
- Registered ownership: Identifies the legally registered property owner.
- Mortgage annotation: Records the mortgage or related security arrangement against the property.
- Original title custody: Refers to who physically holds the relevant title documents.
A lender may require custody of certain original property documents during the financing period.
For Asialink Finance Corporation’s applicable real estate mortgage arrangements, the original owner’s duplicate Transfer Certificate of Title (TCT) or Condominium Certificate of Title (CCT) is kept in the company’s custody for the duration of the financing arrangement, subject to the applicable terms and requirements.
This document custody does not, by itself, mean ownership has transferred to Asialink.
Other financing providers may have different requirements. Borrowers should confirm which documents must be submitted, how they will be handled, and when they may be returned.
What Happens After the Loan Is Fully Paid?
Once the secured obligation has been fully satisfied, the borrower may proceed with the mortgage release process.
The general steps include:
- Confirming full settlement: The lender verifies that the outstanding balance and applicable obligations have been paid.
- Preparing release documents: The lender processes the necessary mortgage discharge or cancellation documents.
- Returning retained documents: Original documents held by the lender are prepared for collection or release.
- Updating property records: The borrower completes applicable procedures to reflect the cancellation of the mortgage annotation.
For Asialink borrowers, the company notifies them when the collateral and necessary release documents are ready.
Borrowers must personally visit the designated branch to complete the applicable collection procedures.
Under Asialink’s stated policy, documents should be claimed within 60 days after notification. A ₱1,500 retrieval or reprocessing fee applies when documents remain unclaimed beyond this period and the borrower later requests retrieval or reprocessing.
The processing period may vary depending on documentation and account requirements. Borrowers should confirm the applicable release arrangements with the branch handling their loan.
What Is Mortgage Redemption Insurance in the Philippines?
Mortgage Redemption Insurance (MRI) in the Philippines is an insurance arrangement that may help cover an outstanding mortgage obligation if the insured borrower dies, subject to the policy’s coverage, exclusions, and conditions.
MRI is generally designed to reduce the financial burden associated with an unpaid mortgage following a covered event.
Important considerations include:
- Coverage: The policy specifies the insured events and applicable benefits.
- Outstanding balance: Insurance proceeds may be applied toward the covered mortgage obligation.
- Exclusions: Certain circumstances may not qualify for payment.
- Premiums: The borrower may need to pay insurance premiums under the applicable arrangement.
- Claims: Required documents and procedures depend on the insurance provider.
For example, if an insured borrower dies while a mortgage remains outstanding, an approved MRI claim may help settle the covered balance.
However, insurance does not automatically guarantee full repayment. Coverage limits, exclusions, and claim conditions must be reviewed.
Mortgage Redemption Insurance is also different from property insurance, which generally addresses specified damage or loss affecting the insured property.
Borrowers should ask whether MRI is required, who provides the coverage, how premiums are calculated, and what circumstances are covered.
MRI availability and requirements vary by financing provider. Its application to Asialink’s mortgage financing products should be confirmed directly with the company.
Mortgage in Tagalog: Ano ang Mortgage?
Kung ang tanong mo ay “What is mortgage in Tagalog?”, ang mortgage ay isang kasunduan kung saan ginagamit ang isang ari-arian, tulad ng bahay o lupa, bilang collateral o garantiya para sa utang.
Hindi ibig sabihin nito na awtomatikong mapupunta sa nagpapautang ang pagmamay-ari ng ari-arian.
Habang may natitirang obligasyon, kailangang magbayad ang nangutang ayon sa napagkasunduang mga kondisyon.
Kung hindi matutupad ang mga obligasyon, maaaring magkaroon ng legal na proseso na makaaapekto sa ari-ariang ginamit bilang collateral.
Simpleng Kahulugan ng Mortgage
Ang simpleng mortgage in Tagalog ay paggamit ng ari-arian bilang seguridad sa isang utang.
Halimbawa, kung mayroon kang lupa at nais mo itong gamitin bilang collateral sa isang loan, maaaring magkaroon ng mortgage sa lupa.
Mahalagang tandaan ang mga sumusunod:
- Mananatili kang responsable sa pagbabayad ng utang.
- Ang lupa ay magsisilbing collateral habang may obligasyong kailangang bayaran.
- Hindi awtomatikong lilipat ang pagmamay-ari ng lupa sa nagpapautang.
- Maaaring magkaroon ng legal na epekto kapag hindi natupad ang kasunduan.
Bago pumirma, basahin ang mga kondisyon tungkol sa pagbabayad, interes, bayarin, at collateral.
Halimbawa ng Mortgage sa Pilipinas
Halimbawa, si Ana ay may bahay na nakapangalan sa kanya. Kailangan niya ng karagdagang puhunan para sa kanyang negosyo.
Ganito maaaring gumana ang mortgage:
- Nag-apply si Ana para sa financing.
- Sinuri ng lender ang kanyang mga dokumento, kakayahang magbayad, at ari-arian.
- Matapos maaprubahan ang aplikasyon, ginamit ang bahay bilang collateral.
- Nagbayad si Ana ayon sa napagkasunduang iskedyul.
- Pagkatapos mabayaran ang buong obligasyon, sinimulan ang naaangkop na proseso para sa release ng mortgage.
Ipinapakita ng halimbawang ito na ang mortgage ay may kasamang pananagutan sa pagbabayad at mga legal na kondisyon.
Hindi rin garantisado ang pag-apruba ng loan dahil lamang may ari-ariang maaaring gawing collateral.
What Should You Check Before Taking a Mortgage Loan?
Before signing a mortgage agreement, review both the financing costs and the conditions affecting your property.
A careful assessment can help you understand whether the repayment schedule is manageable and what responsibilities you are accepting.
Interest Rates, Fees, and Repayment Terms
The interest rate is only one part of the total borrowing cost.
Review the following details before accepting a financing offer:
- Interest or financing rate: Check how the rate is calculated and applied.
- Processing and other fees: Identify charges included in or added to the financing.
- Repayment frequency: Confirm whether payments are monthly or follow another schedule.
- Loan term: Understand how long repayment will continue.
- Total repayment amount: Request a breakdown of the expected overall payment obligation.
- Late-payment provisions: Review applicable penalties and consequences of missed payments.
- Early repayment conditions: Check whether advance settlement involves additional fees or adjustments.
Ask for a written explanation if any term is unclear.
A lower monthly payment does not necessarily mean a lower overall borrowing cost.
Property and Collateral Conditions
Property ownership alone does not guarantee eligibility for a mortgage.
Before applying, review whether the property meets the financing provider’s requirements.
Important factors include:
- Property type and intended use
- Registered ownership and supporting title documents
- Appraised property value
- Location, access, and physical condition
- Existing legal claims, debts, or restrictions attached to the property
- Applicable collateral and transfer restrictions
For jointly owned or corporate-owned properties, additional ownership and authorization documents may be necessary.
Borrowers should also clarify whether the proposed collateral has existing obligations that could affect the financing assessment.
Title, Insurance, and Release Conditions
A mortgage agreement may involve obligations beyond regular loan payments.
Before signing, confirm:
- Who will hold the original property title documents
- Whether a mortgage annotation will be registered
- Whether MRI or other insurance coverage is required
- Who pays insurance premiums and related charges
- What documents will be issued after full repayment
- How the mortgage cancellation process works
- When and where retained documents may be collected
These questions help establish what happens throughout the financing arrangement, including after the debt has been fully paid.
Document custody, insurance, and release procedures should always be confirmed with the financing provider.
Can You Use Property as Collateral With Asialink?
Asialink Finance Corporation offers real estate mortgage financing/Sangla Titulo arrangements, subject to eligibility requirements and property evaluation.
These products allow eligible property owners to apply for financing using qualifying real estate as collateral.
The company also offers separate Real Estate Financing solutions for eligible property purchases. Property-backed borrowing and purchase financing serve different purposes and have different requirements.
You can review the available options through Asialink’s financing products.
What Property Types May Be Considered?
Residential properties may be considered for Asialink’s real estate mortgage financing, subject to the applicable product requirements.
Certain commercial or industrial properties may also be evaluated where permitted under the relevant financing arrangement.
Acceptance depends on several considerations:
- Property classification and legal ownership
- Physical condition and accessibility
- Location and surrounding property characteristics
- Availability of required ownership documents
- Property inspection and appraisal results
- Applicable financing product guidelines
Not every residential, commercial, or industrial property will qualify.
Applicants should confirm the accepted property categories directly with Asialink before preparing an application.
What Factors Affect Property Eligibility and Loan Amounts?
The amount available under Asialink’s real estate mortgage financing depends on the product’s applicable maximum financing limit and the company’s internal Loan-to-Value (LTV) evaluation.
LTV compares the proposed financing amount with the property’s appraised value. The lender’s internal assessment determines how this relationship affects the application.
Other relevant factors may include:
- Location and accessibility: Whether the property can be inspected and evaluated under the company’s requirements.
- Property appraisal: The assessed value and condition of the proposed collateral.
- Ownership: Whether the applicant has the required legal rights over the property.
- Repayment capacity: The applicant’s documented financial ability to meet the obligation.
- Product requirements: The applicable financing limits and eligibility conditions.
Asialink’s REM and Sangla Titulo products may be available to eligible applicants across the Philippines, subject to property location, accessibility, inspection, and appraisal requirements.
For properties owned by a corporation, an authorized representative must have appropriate authority to act on its behalf.
Jointly owned properties may require the involvement and consent of registered co-owners, depending on the applicable legal and financing requirements.
What Documents May Be Required?
Applicants for real estate mortgage financing should prepare the documents required for their particular circumstances.
Possible document categories include:
- Application documents: A completed financing application form and other requested information.
- Identification: Valid government-issued identification documents.
- Proof of income: Employment, business, or financial records relevant to repayment assessment.
- Property ownership records: Applicable title documents, such as an OCT, TCT, or CCT.
- Property-related documents: Tax declarations, relevant tax records, and location information.
- Additional supporting documents: Materials requested during credit assessment, ownership verification, or appraisal.
Depending on the property and financing arrangement, original documents may need to be presented or submitted for verification and mortgage processing.
These are possible requirements rather than a complete checklist. Applicants should confirm the current documentation requirements with Asialink.
Where Can You Ask About Mortgage or Collateral Financing?
Borrowers interested in mortgage or collateral financing can contact an official Asialink Finance Corporation branch for product-specific information or simply email [email protected].
Branch representatives may help explain:
- Available financing products
- General eligibility requirements
- Required application and property documents
- Property assessment procedures
- Applicable financing terms
- Mortgage documentation and release arrangements
Asialink operates branches across the Philippines. You can find an appropriate location through its official branch directory.
Requirements and terms may vary depending on the financing product, collateral, and applicant’s circumstances.
What Should You Ask Before Visiting a Branch?
Preparing questions before contacting a branch can help you understand the application process.
Consider asking:
- What property types are accepted? Confirm whether your property falls under the applicable collateral categories.
- What documents should I prepare? Ask about ownership, identification, financial, and property records.
- Is MRI required? Clarify whether Mortgage Redemption Insurance or another insurance product applies.
- How is the property appraised? Understand the inspection and valuation process.
- What happens to the original title? Confirm document custody and mortgage annotation requirements.
- How does the mortgage release process work? Ask about repayment confirmation, release documents, and collection procedures.
You may also request an explanation of the repayment schedule, total financing cost, and consequences of missed payments.
Conclusion
Understanding what a mortgage is helps you recognize the responsibilities involved when real property is used as collateral.
A mortgage secures a financial obligation without automatically transferring ownership to the lender. However, failure to meet repayment requirements may have consequences involving the property under the agreement and applicable laws.
Before applying for a mortgage loan, review the total borrowing cost, property requirements, title custody, insurance conditions, and mortgage release procedures.
Asialink Finance Corporation offers property-backed financing options for eligible borrowers, including Real Estate Mortgage and Sangla Titulo arrangements. Property acceptance, financing terms, insurance requirements, and document-release procedures depend on the specific product and agreement.
Explore Asialink Finance Corporation’s financing products or contact an official branch to learn about the requirements relevant to your property and financing needs.
FAQs
Can a mortgage be transferred to another person?
A mortgage-related obligation or interest may be transferred or assigned in certain circumstances, subject to applicable laws, contractual terms, and required approvals.
However, transferring property ownership does not automatically transfer the original borrower’s personal repayment obligations.
If you want another person to assume your mortgage loan, discuss the proposed arrangement with your lender and obtain the required documentation before proceeding.
Can you sell a property that still has an existing mortgage?
Yes, a mortgaged property may generally be sold, but the existing mortgage remains an important consideration.
Under Article 2130 of the Philippine Civil Code, a contractual provision prohibiting the owner from selling mortgaged immovable property is void.
However, selling the property does not automatically cancel the mortgage or release the original borrower from their obligations.
Before selling, review the outstanding balance, property records, financing agreement, and appropriate settlement or transfer procedures.
What happens if a mortgaged property is jointly owned?
When a property has multiple registered owners, a mortgage involving the entire property generally requires appropriate authority or participation from the relevant owners.
The legal effect depends on ownership rights, the interest being mortgaged, and the applicable agreement.
Applicants should disclose joint ownership and confirm what signatures, authorizations, or consent documents are required before proceeding.
Can you pay off a mortgage loan early?
Early repayment may be possible, depending on the financing agreement and applicable legal requirements.
Some financing arrangements include prepayment charges, interest adjustments, or other settlement conditions.
Before paying early, ask the lender for the total settlement amount, including any applicable fees, and confirm how the mortgage release process will proceed.
Does having a mortgage affect your ability to apply for another loan?
Having an existing mortgage does not automatically prevent you from applying for another loan.
However, lenders may consider your existing repayment obligations, income, credit history, and overall financial capacity when evaluating a new application.
An existing mortgage may also affect whether the same property can be accepted as collateral for additional financing.
Approval depends on the lender’s credit assessment, product requirements, and applicable collateral conditions.